
Most business owners don’t have a money problem
They have a surprise problem.
You know the feeling. The tax bill lands and it’s twice what you set aside. A supplier invoice shows up that you completely forgot about. Or you finish your busiest month of the year, look at the bank balance, and wonder where all the money went.
None of these moments are really about not earning enough. They’re about not seeing what’s coming until it’s already here. And by then, your options are limited: dip into savings, lean on a line of credit, delay a payment, or scramble.
The good news is that most financial surprises are predictable. They just need a little attention, on a regular schedule. The fix is one simple monthly habit that takes about thirty minutes: compare your budget to your actuals.
Budget vs. actuals: the plan and the reality
This sounds technical, but it isn’t.
- Your budget is the plan. It’s what you expect to bring in and what you expect to spend in a given month.
- Your actuals are what really happened. They’re the real sales and the real expenses, pulled from your bank statements or bookkeeping software.
Once a month, you put the two side by side and ask one question: Where’s the gap, and why?
That’s it. You don’t need complex spreadsheets, accounting software expertise, or a finance degree. A simple two-column list is enough to start. What matters is that you look, consistently, every month.
Why monthly matters: April vs. December
Imagine you planned to spend $4,000 a month on materials, but you actually spent $6,500.
If you catch that in April, it’s a $2,500 problem. You can ask your supplier about pricing, check whether you’re over-ordering, adjust your quotes to customers, or shift other spending to compensate. You have eight months to course-correct.
If you don’t catch it until December, it’s been happening all year. That’s potentially $20,000 or more in unplanned spending, and the year is already over. At that point, you’re not managing the problem. You’re just absorbing it.
The numbers are exactly the same in both cases. The only difference is when you found out. A monthly check turns big, painful year-end discoveries into small, fixable monthly adjustments.
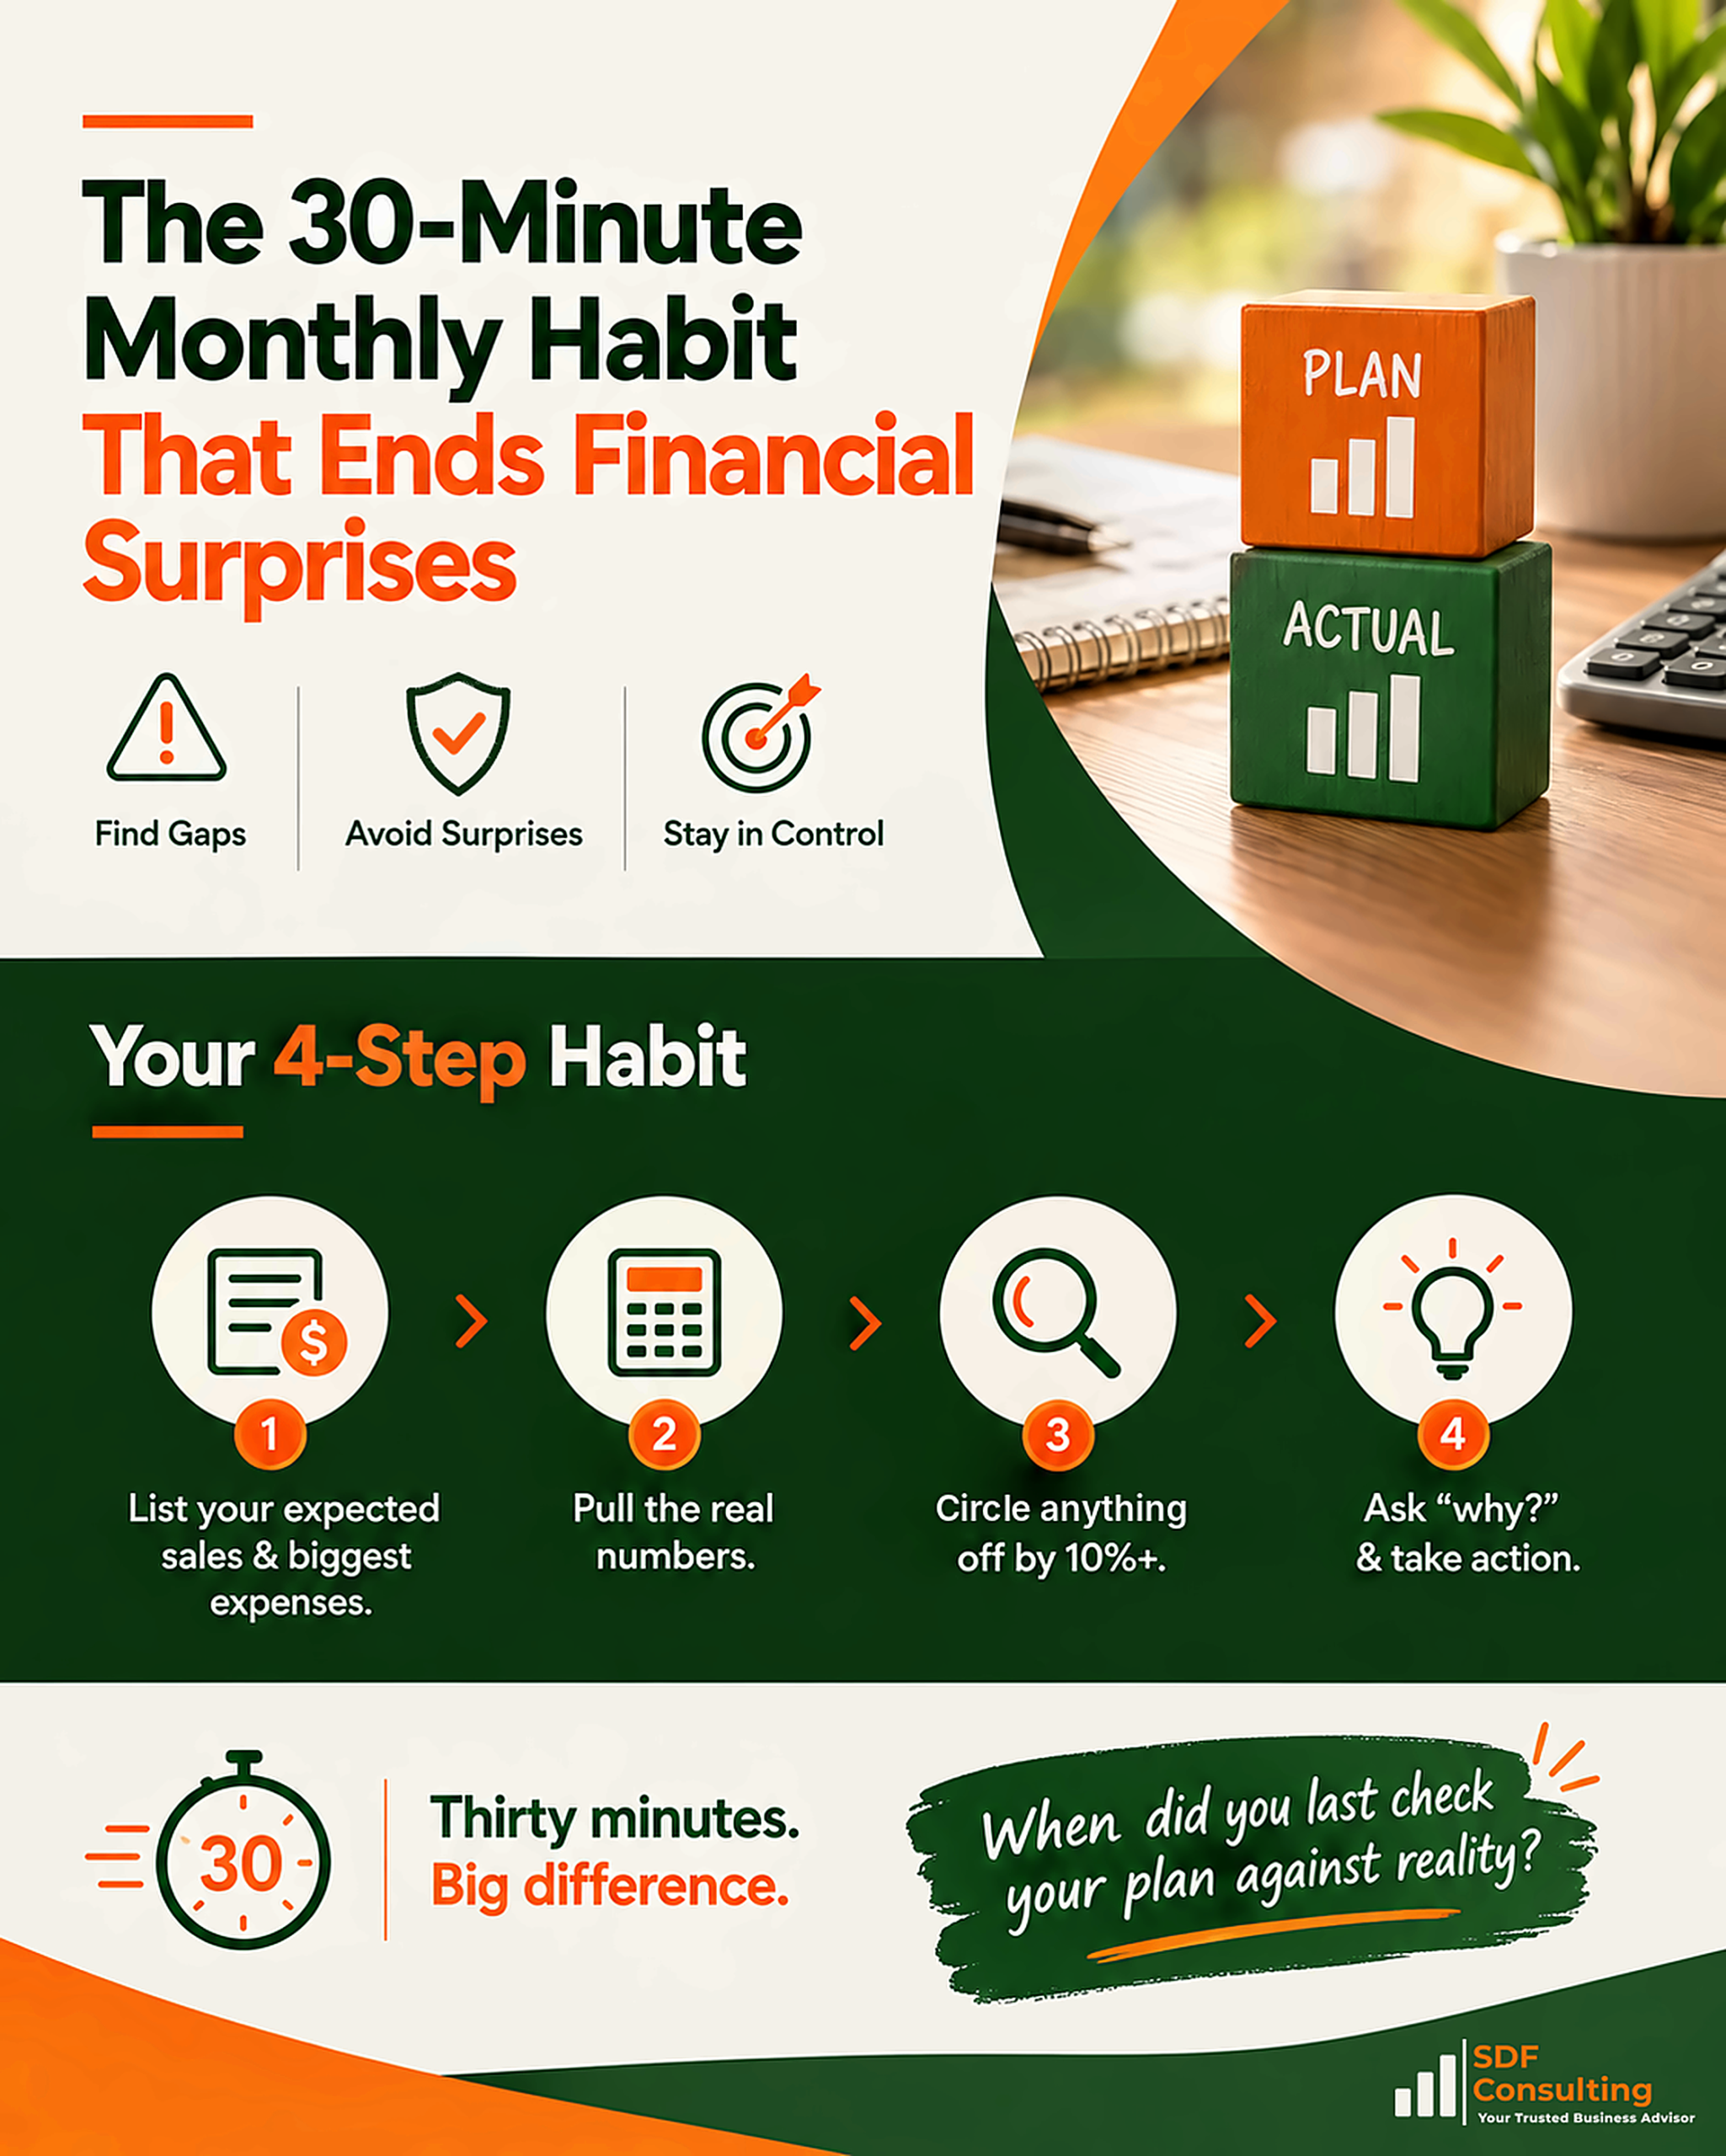
The 30-minute habit, step by step
You can start this month. Here’s how.
1. List your expected sales and biggest expenses
At the start of the month, write down what you expect to earn and your largest costs. Don’t try to track every coffee and paper clip. Focus on the five to ten items that really move the needle: sales, payroll, rent, materials or inventory, marketing, and any big one-time costs you know are coming. Last month’s numbers are a perfectly good starting point.
2. At month-end, pull the real numbers
When the month closes, grab your actual figures from your bank statements, credit card statements, or accounting software. Put them right next to your plan.
3. Circle anything off by more than 10%
Not every difference deserves your attention. A rule of thumb: if a line is off by more than 10% (in either direction), circle it. Small variances are normal noise. Big ones are signals.
Here’s what that might look like:
- Sales: planned $30,000, actual $28,500. Off by 5%, so no circle.
- Materials: planned $4,000, actual $6,500. Off by 63%, circle it.
- Payroll: planned $12,000, actual $12,300. Off by 3%, so no circle.
- Marketing: planned $1,500, actual $900. Off by 40%, circle it.
- Rent: planned $2,500, actual $2,500. Right on target.
In this example, two lines need a closer look: materials and marketing.
4. Ask “why?” and decide what to do
For each circled item, ask why it happened, then decide on one action. Was it a one-time event, or the start of a trend? Is it something to fix, something to plan for, or something to celebrate?
Underspending deserves a “why?” too. In the example above, marketing came in $600 under budget. Is that a smart saving, or did a campaign quietly not happen, which might explain the softer sales?
What the gaps usually tell you
Once you start asking “why?”, you’ll notice the same causes come up again and again:
- Costs rising month after month often mean supplier price increases. Renegotiate, compare suppliers, or update your pricing.
- A one-off spike is usually a bulk purchase or unexpected repair. Note it, and plan for it next time.
- Sales below plan can come from seasonality, a lost client, or slower collections. Adjust the forecast and follow up on overdue invoices.
- Spending creep is often subscriptions and small costs adding up. Review recurring charges and cancel what you don’t use.
- A big bill you didn’t budget for is usually an annual or quarterly cost like tax, insurance, or licences. Set aside a monthly amount for it going forward.
The last one is behind many of those “surprise” tax bills. Once a cost is on your radar, you can spread it across the year instead of being hit all at once.
Making the habit stick
The hardest part isn’t the math. It’s remembering to do it. A few things help:
- Book it in your calendar. Pick a fixed slot, like the first Tuesday of every month, and treat it like a client meeting.
- Keep it simple. One page, one table. If it takes hours, you won’t keep doing it.
- Update your plan as you learn. If materials really cost $6,500 now, next month’s budget should say so.
- Write down your decisions. A short note on each circled item makes next month’s review faster and shows you whether your fixes worked.
After three or four months, you’ll start spotting patterns before they become problems. That’s when the habit really pays off.
Stay in control instead of being surprised
Thirty minutes a month. That’s what it takes to stay in control of your business instead of being surprised by it.
So here’s the question: when did you last check your plan against reality?
If the honest answer is “I can’t remember”, this is the month to start. And if you’d like help setting up a simple budget, building your first budget-vs-actuals review, or making sense of what the numbers are telling you, SDF Consulting is here to help. Reach out at arshad@sdfconsulting.ca
SDF Consulting: Your Trusted Business Advisor.