
You Don’t Have a Profit Problem — You Have a Timing Problem
Most business owners think they have a profit problem.
What they actually have is a timing problem.
I’ve worked with owners who were “profitable on paper” and still couldn’t make payroll. Confusing, right? The P&L says you’re winning. The bank account says otherwise. The accountant nods and says the numbers look good. Meanwhile, you’re moving money between accounts just to cover Friday’s payroll run.
This isn’t a rare edge case. It’s one of the most common — and most dangerous — blind spots in business ownership.
Here’s the truth every CFO knows, and every founder eventually learns the hard way:
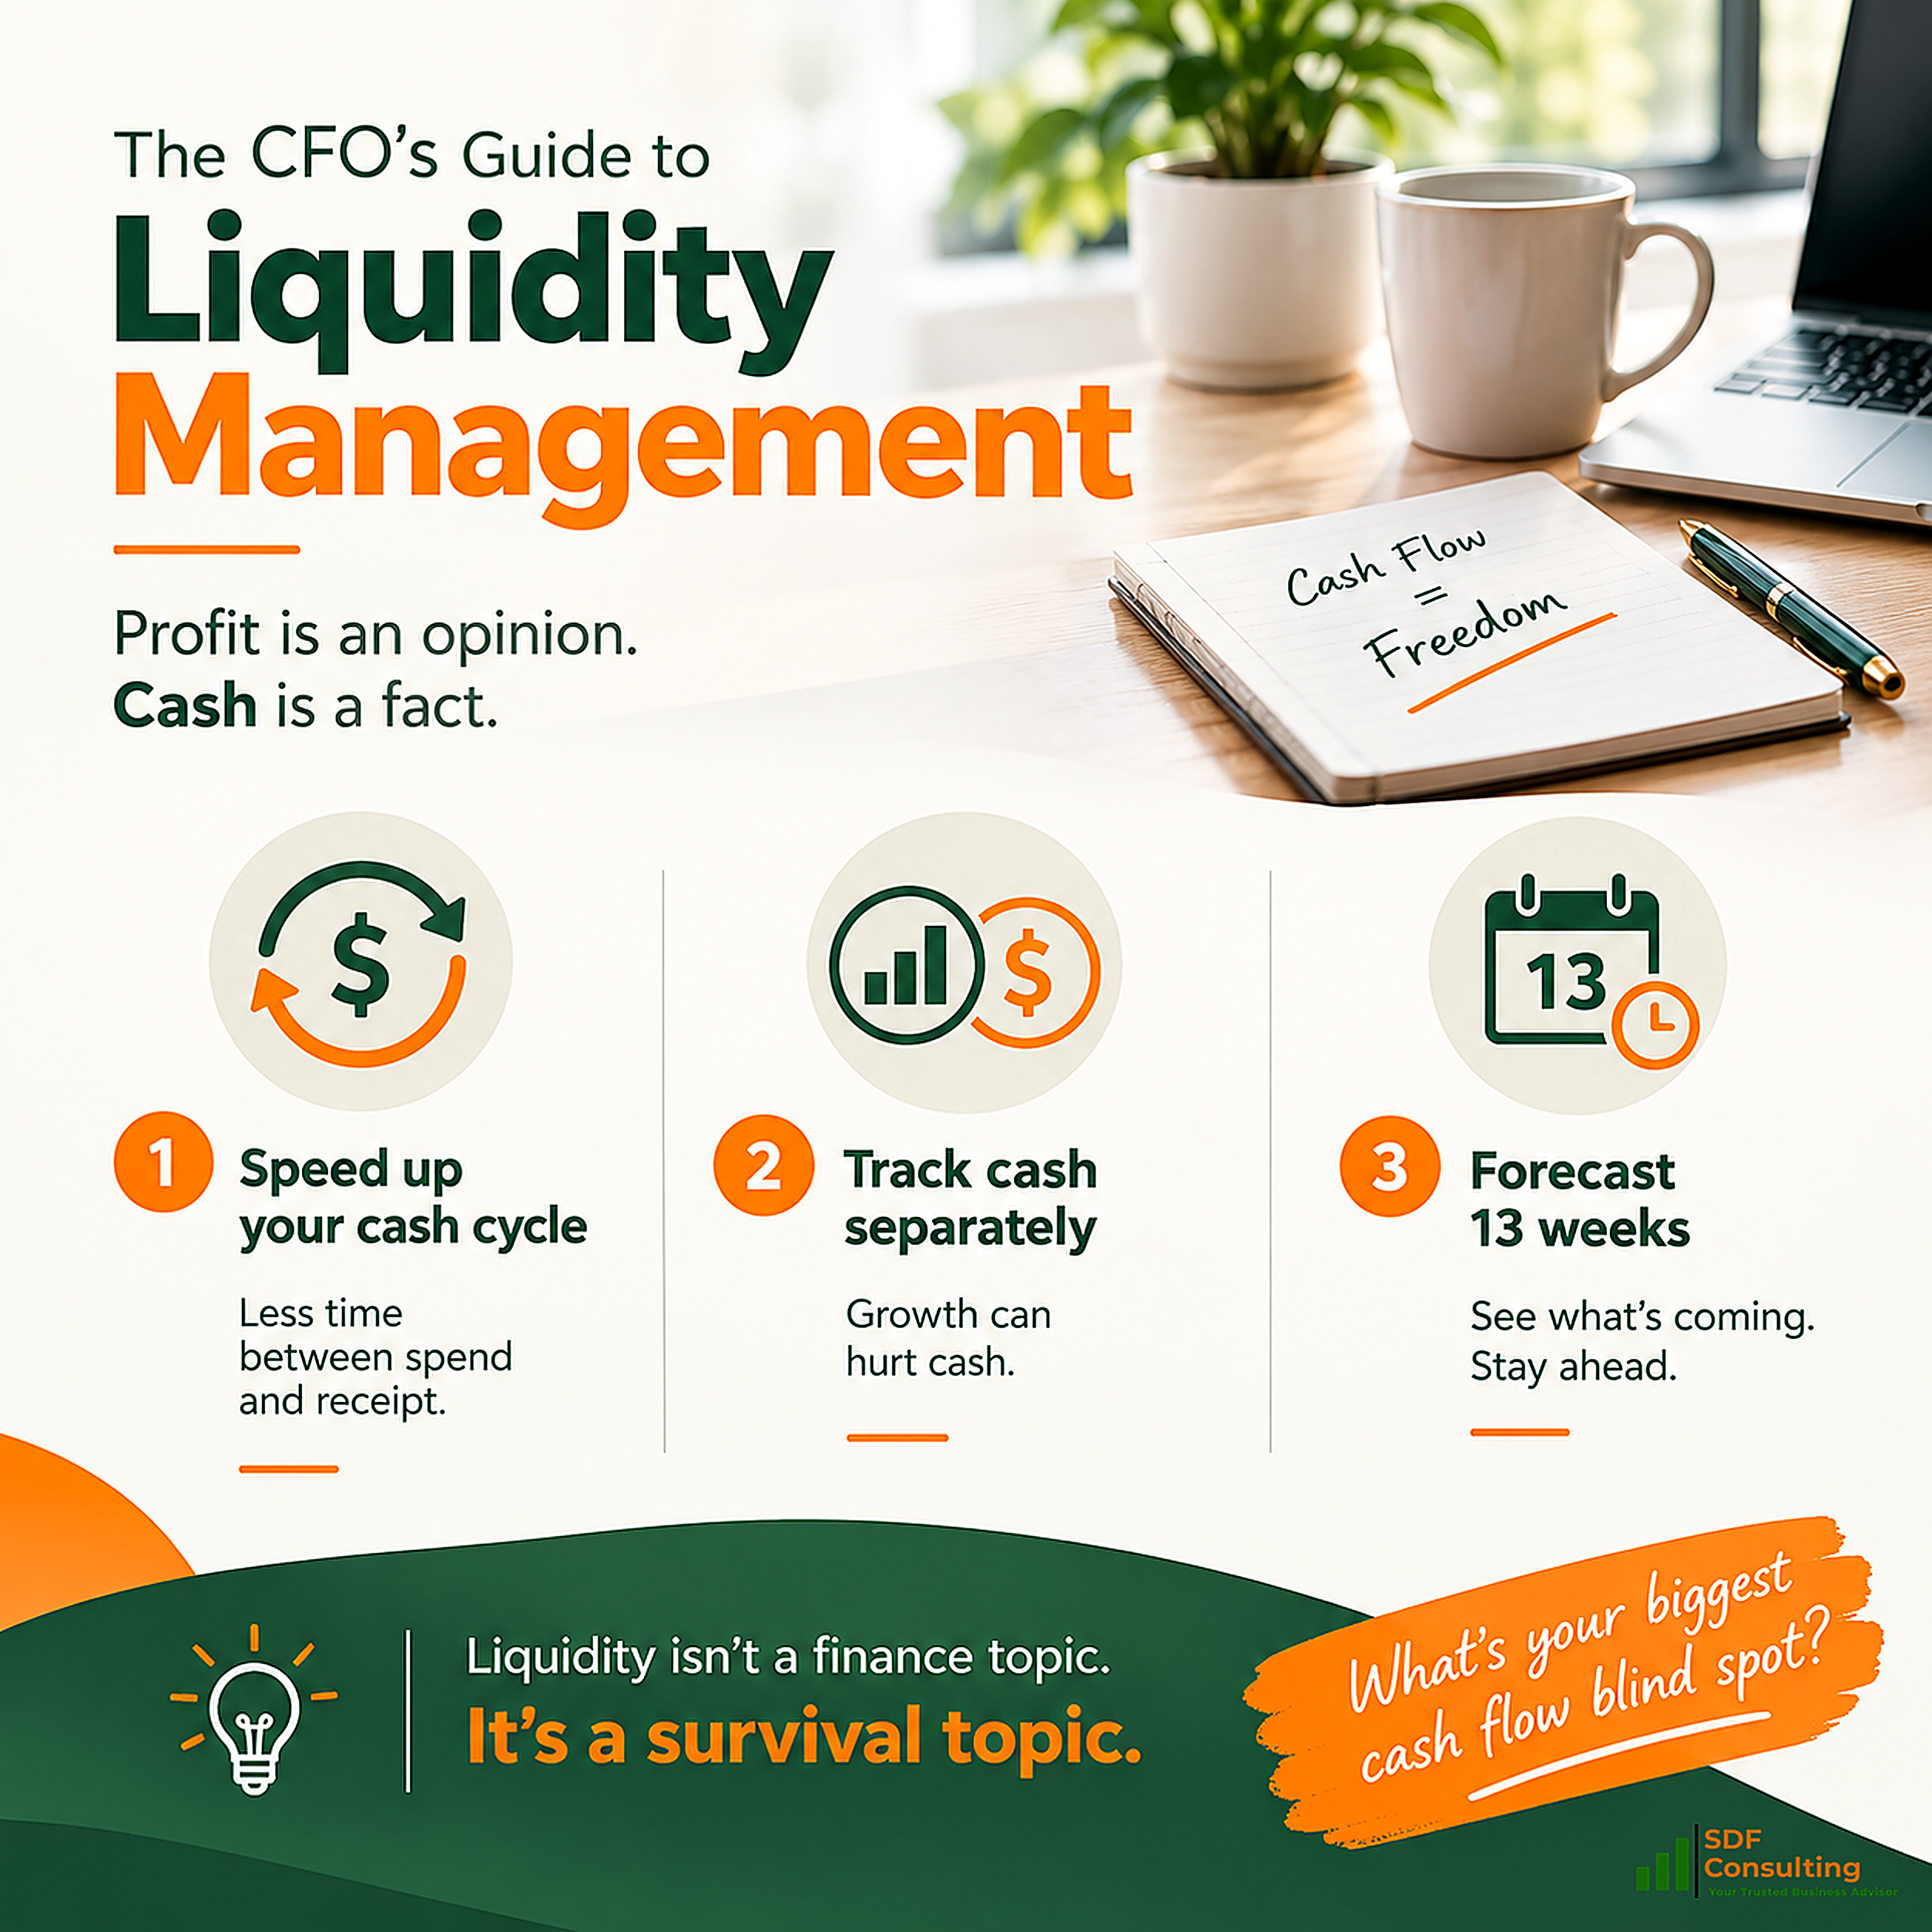
Profit is an opinion. Cash is a fact.
Why Profitable Businesses Still Go Broke
Profit is a calculation. It depends on accounting rules, timing assumptions, and judgment calls — when revenue is recognized, how expenses are matched, how depreciation is spread out. Two accountants can look at the same business and, within the rules, arrive at slightly different profit figures.
Cash doesn’t have that flexibility. Cash is binary. It’s either in the account or it isn’t.
A sale can be booked the moment a contract is signed, but the money might not actually arrive for 30, 60, or even 90 days. In the meantime, payroll still runs every two weeks. Rent is still due on the first. Suppliers still expect payment on their terms, not yours.
That gap — between when a business looks profitable and when it’s actually solvent — is where trouble quietly builds. It doesn’t show up in a dramatic way at first. It shows up as a tighter month than expected. Then a scramble to cover an invoice. Then a call to a line of credit that used to feel like a safety net and now feels like a lifeline.
By the time it becomes an emergency, it’s often been building for months.
The Real Cost of Ignoring Liquidity
When cash flow isn’t actively managed, the damage isn’t limited to a few stressful weeks. It compounds:
- Missed opportunities. Owners turn down growth, new hires, or bulk-discount inventory purchases — not because the business can’t afford them on paper, but because there isn’t enough cash on hand right now.
- Expensive debt. Businesses that run out of runway often turn to short-term financing at high interest rates, simply because they didn’t see the shortfall coming early enough to negotiate better terms.
- Strained relationships. Late payments to vendors or delayed payroll erode trust — with suppliers, employees, and lenders — even when the business is fundamentally healthy.
- Owner burnout. Few things are more exhausting than running a business that looks successful from the outside while feeling like a constant fire drill on the inside.
None of this is really a profitability issue. It’s a visibility issue. Owners can’t manage what they can’t see, and most financial statements aren’t built to show cash timing clearly.
Three Habits That Fix This Fast
The good news: you don’t need a finance degree to close this gap. You need a handful of habits that any owner can build into a normal week.
1. Know Your Cash Conversion Cycle
Your cash conversion cycle is the time between the day you spend a dollar and the day you get it back. It covers the full loop: cash goes out to buy inventory or deliver a service, then it sits — in inventory, in work-in-progress, in an unpaid invoice — before it finally comes back in.
Shrink that gap, and you free up cash without selling anything new. This is one of the most overlooked levers in a business. Owners chase growth to solve cash problems when tightening the existing cycle would solve it faster and without added risk.
A few practical ways to shorten it:
- Invoice faster. Send the invoice the day the work is done, not at the end of the month.
- Tighten payment terms. Even moving clients from Net 60 to Net 30 makes a real difference at scale.
- Follow up on overdue invoices systematically. Most collections issues aren’t about difficult clients — they’re about the absence of a follow-up process.
- Negotiate better terms with your own suppliers. If you can pay in 45 days instead of 15, that’s cash sitting in your account longer.
- Manage inventory more precisely. Cash tied up in slow-moving inventory is cash that isn’t working for you.
Each of these levers might only move the needle by a few days. But a few days across every transaction, every month, adds up to real breathing room.
2. Track Cash Separately From Revenue
Growth often kills cash, not profit. This is one of the most counterintuitive truths in business finance — the moments that feel like the biggest wins are often the moments of greatest cash risk.
A big new contract can look like a win on the P&L while leaving you broke for 90 days. Why? Because you may need to hire, buy materials, or ramp up capacity before you see a dollar of that new revenue. You’re funding the growth out of pocket long before it pays you back.
This is exactly why revenue and cash need to be tracked as two separate things, not one blended number:
- Revenue tells you whether the business model works — whether people want what you sell and will pay for it.
- Cash tells you whether the business can survive long enough to prove that model works.
A business can have record-breaking revenue and still run out of cash. It happens constantly, especially with businesses that are scaling quickly, taking on longer-term contracts, or expanding into new markets. Watching both numbers side by side — not just the top line — is what keeps growth from becoming a liquidity crisis.
3. Build a Simple 13-Week Cash Flow Forecast
This isn’t a budget, and it isn’t complicated. A budget tells you what you planned to spend. A cash flow forecast tells you what’s actually coming in, what’s actually going out, and what’s left — updated weekly, thirteen weeks at a time.
Why 13 weeks? It’s long enough to see real patterns and seasonal dips coming, but short enough to stay accurate and actionable. A 12-month forecast is guesswork past month three. A 13-week forecast is a living, working tool.
At its simplest, it needs three lines:
- Cash in — expected collections, by week
- Cash out — payroll, rent, suppliers, loan payments, taxes, by week
- Net cash position — what’s left at the end of each week
Update it weekly with real numbers, and it becomes an early warning system. You’ll see a tight week coming a month in advance — plenty of time to accelerate collections, delay a discretionary purchase, or arrange financing on your terms instead of in a panic.
This one habit, more than almost anything else, is what separates businesses that get surprised by cash crunches from businesses that see them coming and route around them.
Bringing the Three Habits Together
None of these three habits are difficult in isolation. The real power comes from doing them together, consistently:
- Shortening the cash conversion cycle reduces how much cash gets tied up in the first place.
- Tracking cash separately from revenue reveals when growth is putting pressure on the business.
- The 13-week forecast shows exactly when and where that pressure will be felt — before it becomes a crisis.
Together, they turn cash flow from something owners worry about reactively into something they manage proactively.
You Don’t Need to Be an Accountant
You just need to start asking the questions a CFO would ask:
- When is this money actually going to hit our account?
- What does the next 13 weeks look like, not just this month?
- Is this new deal going to strengthen our cash position or strain it?
These aren’t technical questions. They’re ownership questions. Any business owner, regardless of financial background, can ask them — and asking them consistently is what changes outcomes.
Liquidity isn’t a finance topic reserved for the back office or the year-end review. It’s a survival topic that belongs on every business owner’s desk, every week.
The Question Worth Asking Yourself
What’s your business’s biggest cash flow blind spot right now?
Is it slow-paying clients? A cash conversion cycle that’s longer than it needs to be? Growth that’s outpacing your cash reserves? Or simply not having a forecast at all?
Whatever it is, the first step isn’t a bigger accounting system or a finance hire. It’s asking the question — and then building the habit of asking it again, every single week.